You made a profit on Bitcoin or another coin at an overseas exchange, and you are not sure how much tax you owe or how to file for 2026.
Profit made during 2026 is miscellaneous income added to your salary and other income, even on an overseas exchange, and is taxed at 5% to 45% income tax plus 10% resident tax. The 20% separate-taxation law has passed but has not started yet.
This guide is based on the National Tax Agency FAQ (revised December 2025) and Ministry of Finance and Financial Services Agency documents checked on 30 October 2026. It shows whether you must file, roughly how much tax applies and which records to keep.
Conclusion: crypto profit in 2026 is miscellaneous income
- Category: individual profit is in principle miscellaneous income, taxed with other income
- Rate: income tax of 5% to 45% plus 10% resident tax, up to 55% combined
- Timing: selling, swapping or paying with crypto is taxed; holding is not
- Filing: employees paid by one employer file when other income exceeds JPY 200,000 a year
- Reform: 20% separate taxation applies from the start date. 2026 is not covered
This guide explains how the system works. For your own tax amount or income category, ask a licensed tax accountant or the tax office.
Crypto tax rates in Japan: 5% to 45% plus 10%
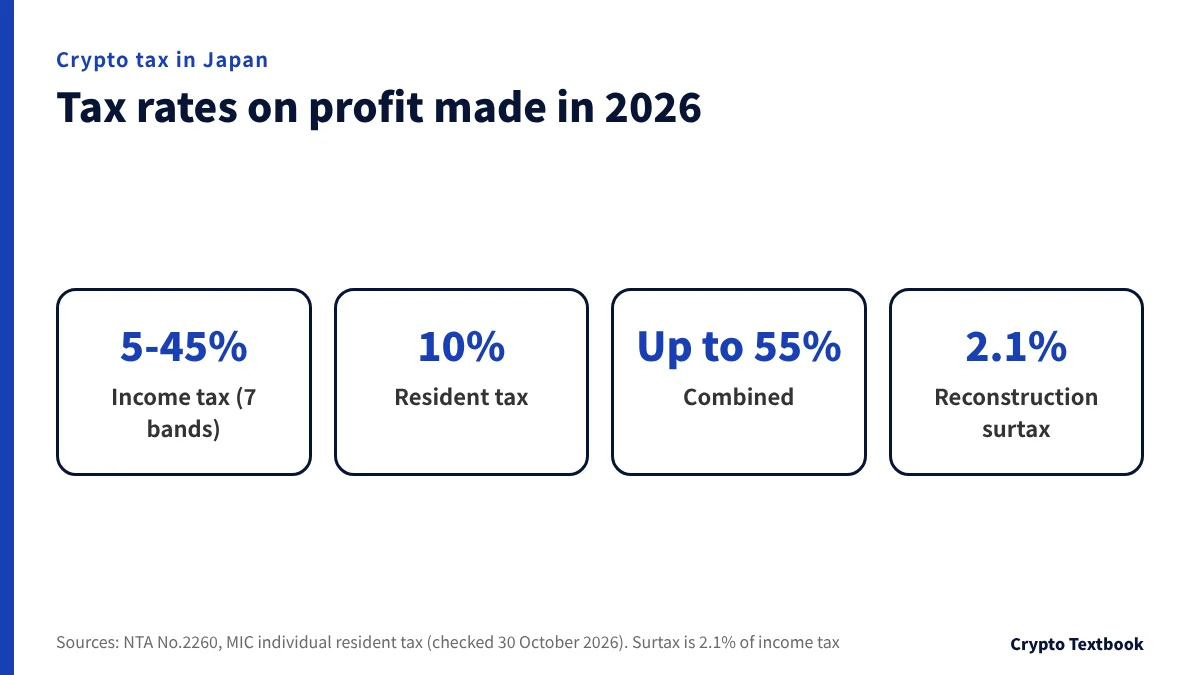
FAQ 2-2 of the National Tax Agency classifies profit from crypto-asset trading as miscellaneous income in principle. It is added to salary and other income, and the tax is worked out on the total.
Domestic FX is taxed separately, but crypto margin trading is excluded from that rule (FAQ 2-12). The more other income you have, the higher the rate on your crypto profit.
| Taxable income | Income tax rate | Deduction | With resident tax |
|---|---|---|---|
| JPY 1,000 to 1,949,000 | 5% | JPY 0 | About 15% |
| JPY 1,950,000 to 3,299,000 | 10% | JPY 97,500 | About 20% |
| JPY 3,300,000 to 6,949,000 | 20% | JPY 427,500 | About 30% |
| JPY 6,950,000 to 8,999,000 | 23% | JPY 636,000 | About 33% |
| JPY 9,000,000 to 17,999,000 | 33% | JPY 1,536,000 | About 43% |
| JPY 18,000,000 to 39,999,000 | 40% | JPY 2,796,000 | About 50% |
| JPY 40,000,000 and above | 45% | JPY 4,796,000 | About 55% |
※ Income tax = taxable income x rate - deduction. The income-based resident tax is 10% (4% prefectural and 6% municipal), according to the Ministry of Internal Affairs and Communications.
The reconstruction surtax is added
A special reconstruction income tax of 2.1% of the income tax amount is added. When a special defence income tax starts in 2027, the combined rate of the two stays the same (No.2260).
Annual revenue above JPY 3 million can change the category
If your trading revenue for the year exceeds JPY 3 million, the category depends on whether you keep books (FAQ 2-2, updated December 2025).
| Situation in the year | Income category (in principle) |
|---|---|
| Revenue of JPY 3 million or less | Miscellaneous income (other) |
| Above JPY 3 million, books kept | Business income |
| Above JPY 3 million, no books | Miscellaneous income (business-related) |
| Used to pay for business purchases | Business income |
※ Even with books, whether it is business income is judged case by case, for example when the trading lacks a profit motive.
From how much is crypto taxed? The JPY 200,000 rule and a quick rate table
When is Bitcoin taxed? Selling, swapping and paying
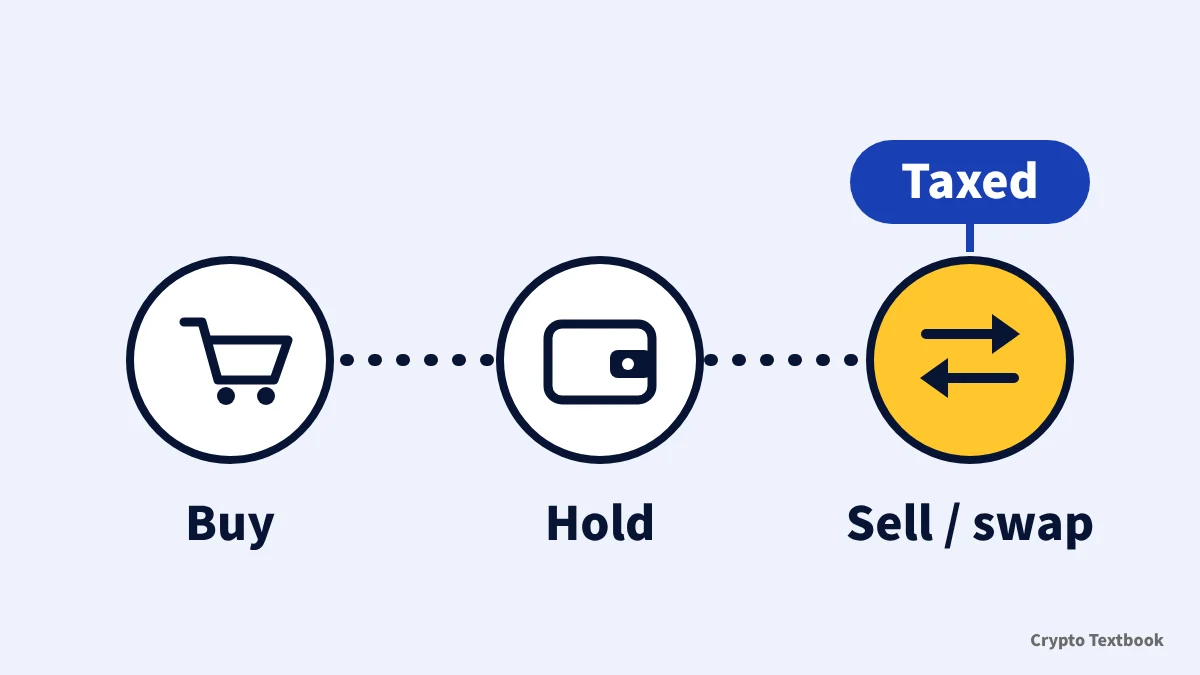
Tax arises when you give up a crypto asset and the gain is fixed. Simply holding an asset that has risen in value is not taxed.
| Transaction | Tax treatment | NTA FAQ |
|---|---|---|
| Selling for yen | Taxed (sale price minus acquisition cost) | 1-1 |
| Paying for goods or services | Taxed (treated as a sale at the price of the goods) | 1-2 |
| Swapping for another crypto asset (BTC to USDT, etc.) | Taxed (calculated at the market value received) | 1-3 |
| Receiving coins from mining, staking or lending | Market value at receipt is income | 1-7 |
| Closing a futures (margin) position | Realised P&L is miscellaneous income | 2-12 |
| Selling short on credit and buying back | Sale price minus buy-back price, income in the year of settlement | 2-13 |
| Holding, or moving coins to your own wallet | Not taxed | - |
The income belongs, in principle, to the year in which the sold coins are delivered. You may instead choose the year in which the sale contract was made (FAQ 2-1).
How a swap is calculated in the FAQ example
In the FAQ 1-3 example, you hand over 1 of 4 BTC bought for JPY 4 million and receive 40 XRP (1 XRP = JPY 30,000). The XRP value of JPY 1.2 million is the BTC sale price; minus the JPY 1 million cost of 1 BTC, the income is JPY 200,000.
Swapping BTC for USDT on an overseas exchange is a swap between crypto assets. It counts as income in the year of the swap, even if you never convert back to yen.
Paying with crypto (FAQ 1-2)
| Item | Amount |
|---|---|
| Purchase | 4 BTC for JPY 4 million (JPY 1 million per BTC) |
| Price of goods paid for | JPY 403,000 (paid with 0.3 BTC) |
| Acquisition cost of 0.3 BTC | JPY 300,000 |
| Income | JPY 403,000 - JPY 300,000 = JPY 103,000 |
How to calculate crypto tax: worked examples
Income is the sale price minus the acquisition cost and fees. In the FAQ 1-1 example, you sell 0.2 of 4 BTC bought for JPY 4 million for JPY 210,000. The 0.2 BTC cost JPY 200,000, so the income is JPY 10,000.
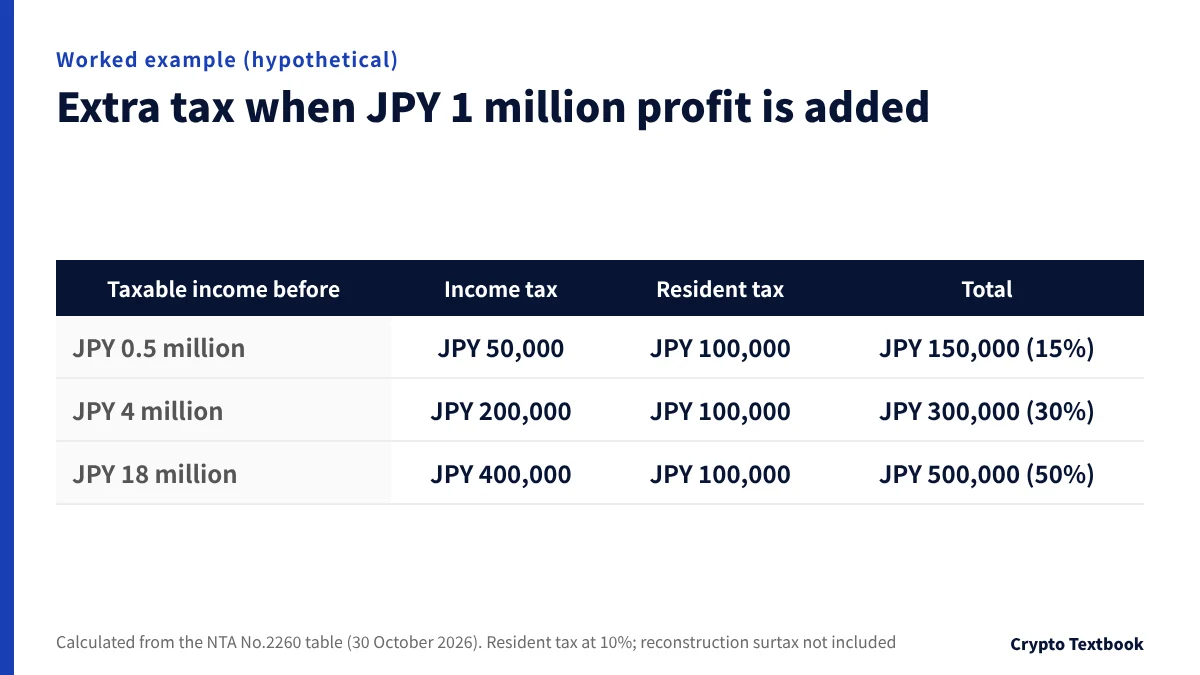
Extra tax from a JPY 1 million profit (hypothetical figures)
The same JPY 1 million profit can raise your tax by more than three times as much, depending on your other income. The figures are hypothetical; only taxable income before the profit changes.
| Taxable income before profit | Extra income tax | Extra resident tax | Total (share of profit) |
|---|---|---|---|
| JPY 0.5 million | JPY 50,000 | JPY 100,000 | JPY 150,000 (15%) |
| JPY 4 million | JPY 200,000 | JPY 100,000 | JPY 300,000 (30%) |
| JPY 18 million | JPY 400,000 | JPY 100,000 | JPY 500,000 (50%) |
※ Example: at JPY 4 million, income tax is JPY 572,500 with the profit and JPY 372,500 without, a difference of JPY 200,000. The reconstruction surtax is not included.
What counts as an expense (FAQ 2-3)
- The cost of the crypto assets you sold
- Fees paid when selling
- The part of internet or PC costs directly needed for selling (internet only if the trading share can be separated)
- A PC used for over a year and above a set price is spread over several years
Total average or moving average for acquisition cost
If you trade the same coin many times in a year, the cost of coins sold is calculated by the total average method or the moving average method. Without a notification, the total average method applies (FAQ 2-4 and 2-5).
To switch methods later, submit an application for approval to the tax office by 15 March of the year you want to switch (FAQ 2-6).
| Item | Total average | Moving average |
|---|---|---|
| Sales for the year (5 BTC) | JPY 5,295,000 | JPY 5,295,000 |
| Cost of coins sold | JPY 3,106,000 | JPY 3,080,200 |
| Income | JPY 2,189,000 | JPY 2,214,800 |
※ The same trades give income that differs by JPY 25,800 depending on the method.
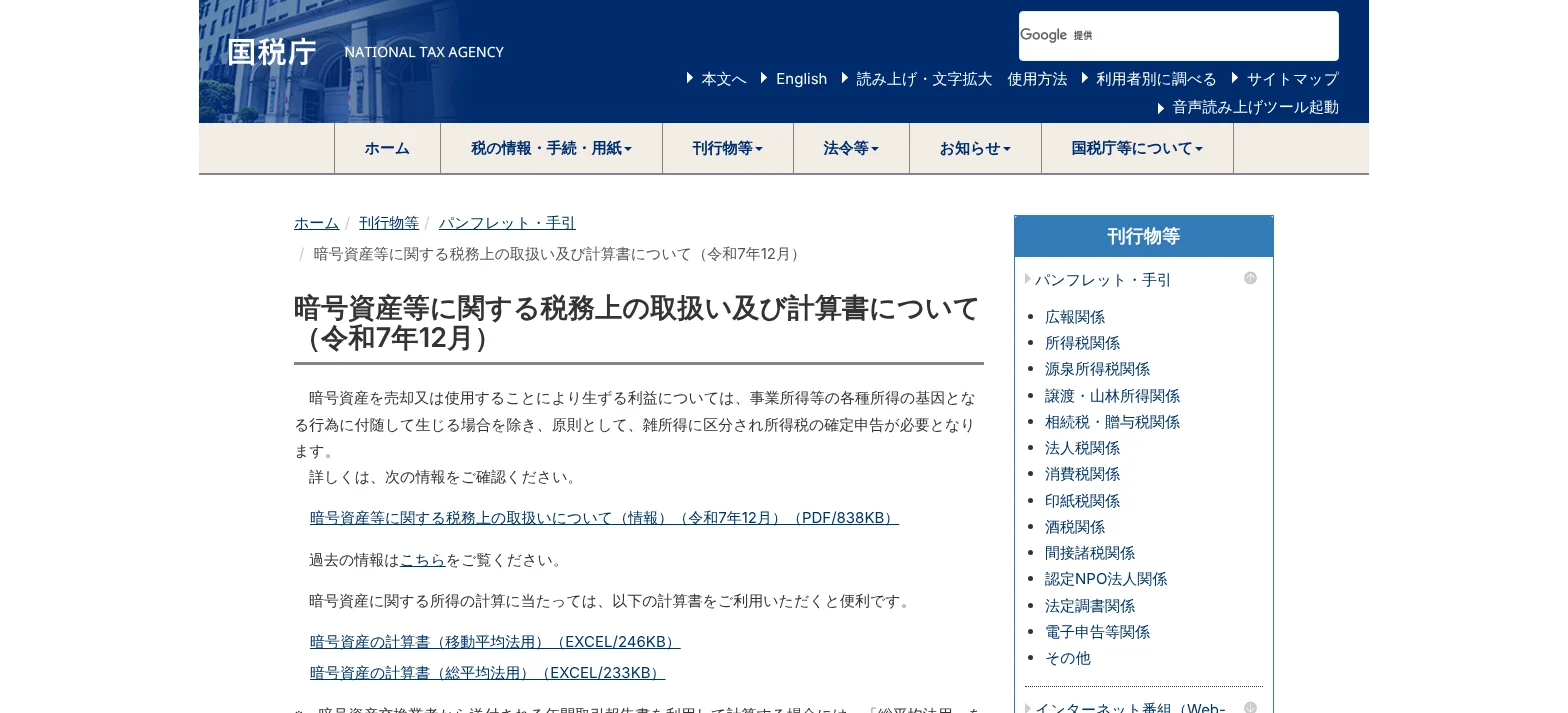
The National Tax Agency offers crypto calculation sheets (Excel) in two versions, for the moving average and total average methods. Enter the year's purchase and sale totals and the sheet gives the income (FAQ 2-8).
How to file a tax return for crypto profit made on overseas exchanges
Who must file: the JPY 200,000 rule and resident tax
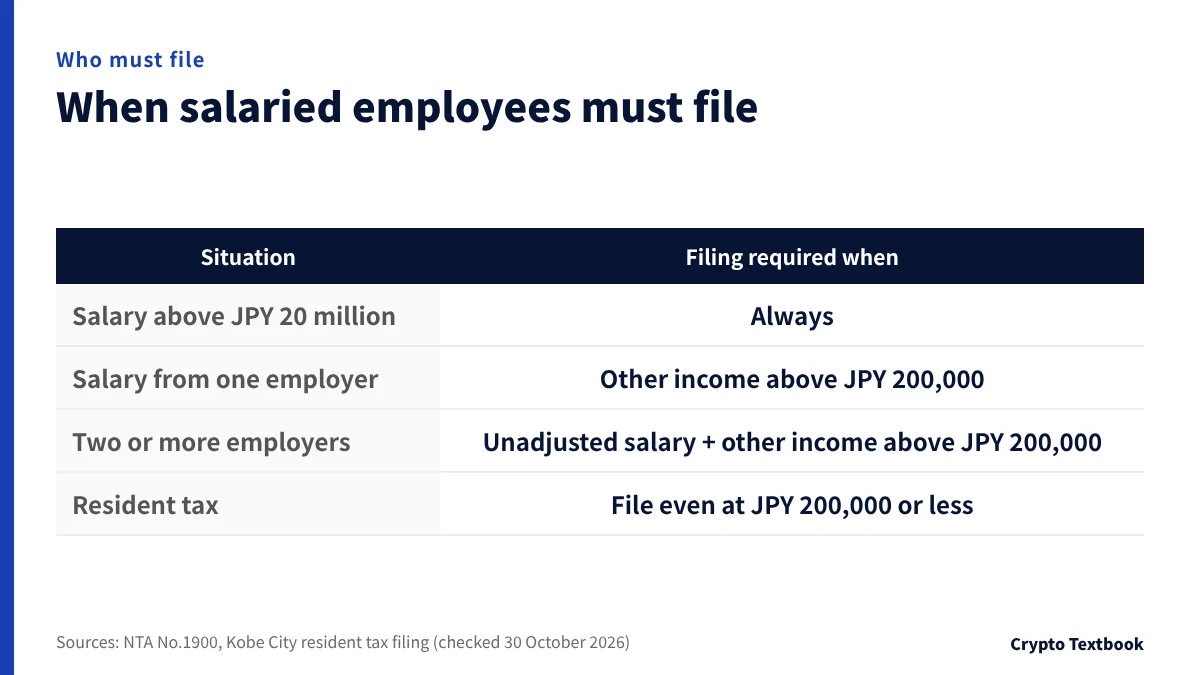
Even with year-end adjustment, employees in any of these three cases under NTA No.1900 must file a return.
| Situation | When a return is required |
|---|---|
| Annual salary above JPY 20 million | Always, regardless of other income |
| Salary from one employer | Income other than salary and retirement income totals more than JPY 200,000 |
| Salary from two or more employers | Salary not covered by year-end adjustment plus other income exceeds JPY 200,000 |
※ The JPY 200,000 test uses income after acquisition cost and fees, not the sale amount.
Not needing an income tax return does not remove the resident tax filing. Kobe City, for example, asks people whose non-salary income is JPY 200,000 or less and who do not file an income tax return to file for resident tax.
In a year when you file for a refund, such as for medical expenses, you must include income of JPY 200,000 or less (NTA note on when a return is not required).
Filing and payment deadlines
The filing period runs from 16 February to 15 March of the year after the profit (No.2024). For 2026, it is Tuesday 16 February to Monday 15 March 2027.
- 01Gather your records
Collect a year of trades, swaps, deposits and withdrawals for each exchange. Save overseas exchange history as CSV.
- 02Work out income per coin
Fill in one calculation sheet from the previous section for each coin.
- 03Prepare the return online
Enter the figures on the NTA return preparation site and the tax is calculated. Submit by e-Tax or by post (No.2024).
- 04Pay by the deadline
File and pay income tax by 15 March. Late payment adds delinquency tax.
Loss-making years: offsetting and carry-forward
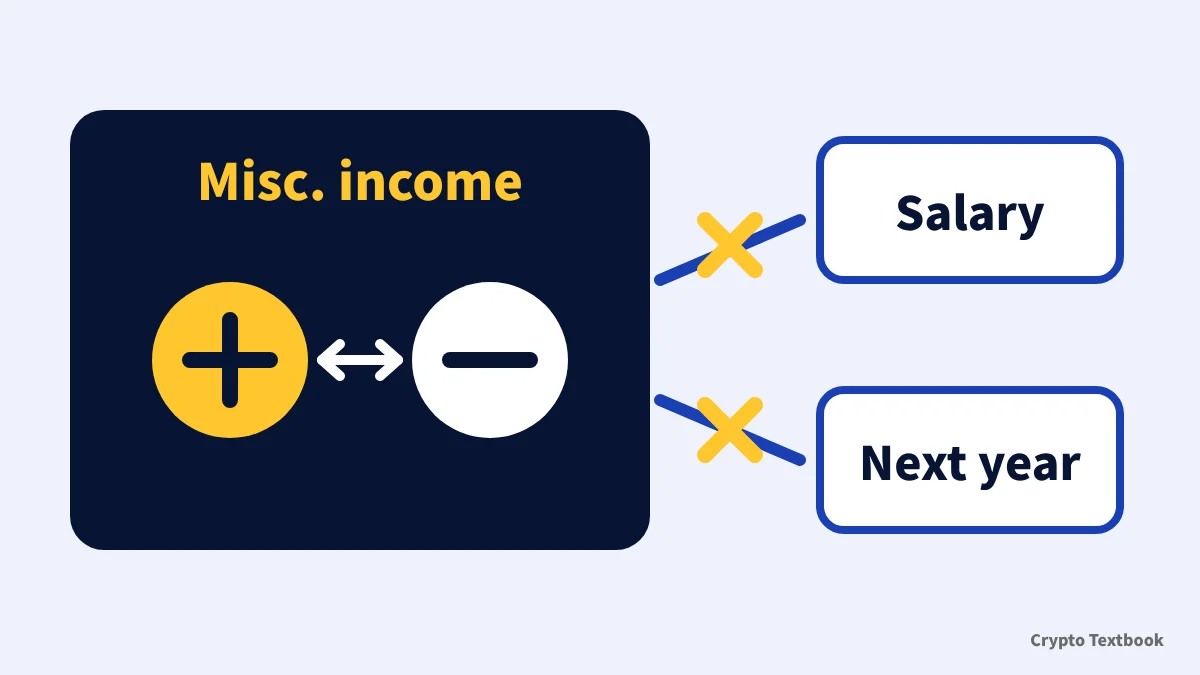
A loss in miscellaneous income cannot be deducted from salary or other income, and there is no rule for carrying it forward (No.2250 and FAQ 2-11).
| What you want to offset | Allowed? |
|---|---|
| Profit on another crypto asset in the same year | Yes |
| Crypto futures profit in the same year | Yes (FAQ 2-12) |
| Salary income or business income | No |
| Gains on shares, funds or FX | No (separately taxed income) |
| Crypto profit in later years | No (no carry-forward) |
Under No.2250, only losses in real estate, business, capital gains and timber income can be offset against other income, and miscellaneous income is not among them.
- Save trade history and conversion rates even in a loss year
- Work out the quantity held at year end and its value
- Next year's cost of coins sold starts from the value held at the start of the year (FAQ 2-4)
A loss realised after 31 December cannot be offset against the previous year's profit. Decide whether to sell on grounds other than tax.
Can crypto losses be carried forward? Offsetting rules and the planned 3-year carry-forward
When does 20% separate taxation start? The FY2026 reform
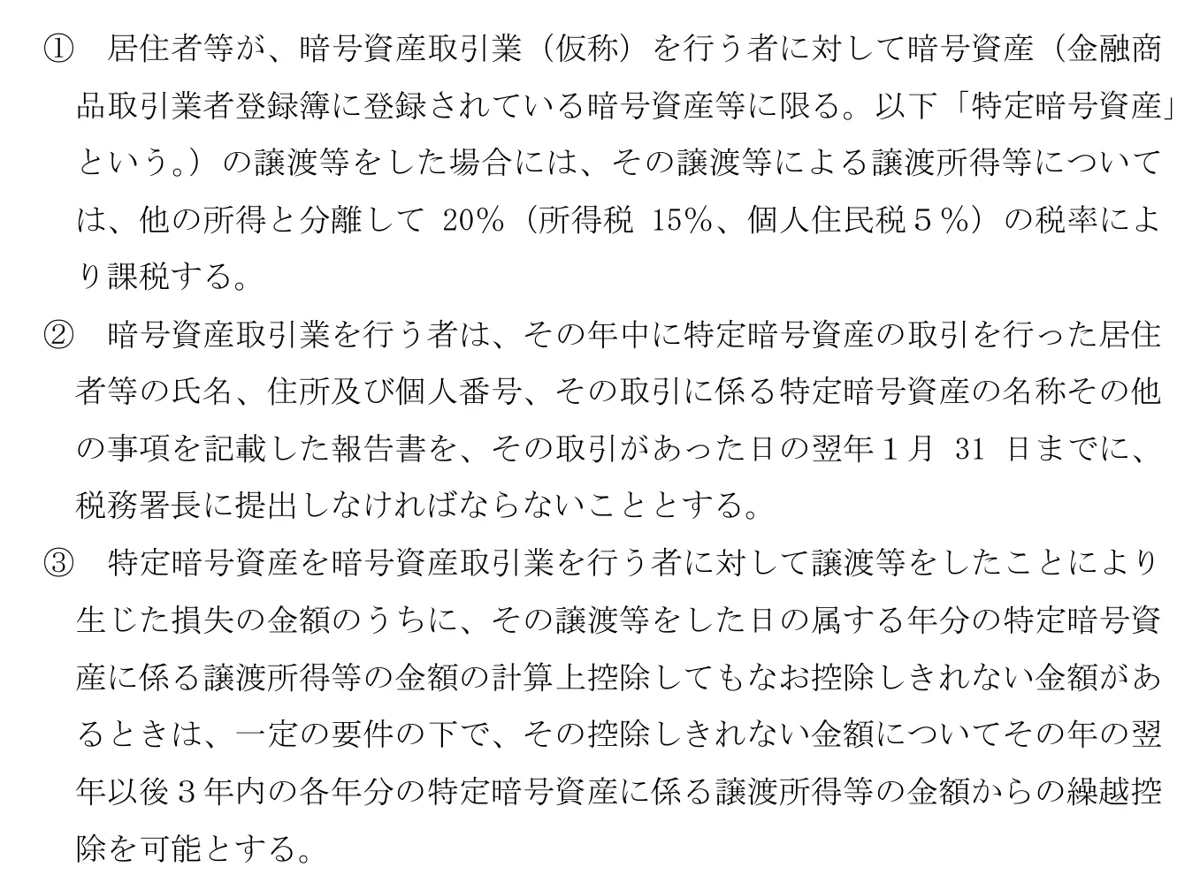
The FY2026 Tax Reform Outline, approved by the Cabinet on 26 December 2025, moves some crypto assets to separate taxation. The rate is 20% (15% income tax and 5% resident tax).
| Date | Event |
|---|---|
| 26 December 2025 | Cabinet approves the Tax Reform Outline |
| 31 March 2026 | Amendment to the Income Tax Act and related laws passed |
| 15 July 2026 | Amended Financial Instruments and Exchange Act passed |
| Within 1 year of promulgation | Amended Act takes effect on a date set by Cabinet Order |
| 1 January of the following year | Start date of separate taxation |
The supplementary provisions of the Income Tax Act amendment set the start as 1 January of the year after the year in which the amended Financial Instruments and Exchange Act takes effect. That Act takes effect on a date set by Cabinet Order within one year of promulgation.
As of 30 October 2026, we have not found a Cabinet Order setting the date. The start is 1 January 2027 if the Act takes effect in 2026, or 1 January 2028 if in 2027. Either way, trades made in 2026 are filed under current rules.
What changes from the start date
| Item | From the start date (specified crypto assets) | Now |
|---|---|---|
| Rate | 20% (15% income tax, 5% resident tax) | 5% to 45% plus 10% resident tax |
| Loss carry-forward | Carry forward for up to 3 years | Not allowed |
| Futures | Derivatives on specified crypto assets move to the futures tax rules | Miscellaneous income, aggregate taxation |
| Reporting | For trades from the year after the start date, dealers report to the tax office by 31 January of the following year | - |
The outline and the bill summary cover selling crypto assets listed in the register of financial instruments business operators to crypto-asset dealers. Neither mentions sales on overseas exchanges.
With the reconstruction surtax, the separate tax rate is 20.315%. The outline has no rule for bringing losses from before the start date into the new system.
Changes for crypto taxed as capital gains
- Crypto taxed as aggregate capital gains loses the special deduction
- The half-taxation rule for assets held over 5 years does not apply
- Losses cannot be offset against other aggregate income
All three are item 6 of section (2) in the outline and apply from income tax for the year after the amended Act takes effect.
Profit on overseas exchanges: filing and records
According to NTA No.2010, most people living in Japan (residents other than non-permanent residents) are taxed on all income, in Japan or abroad. Profit on overseas exchanges such as MEXC or BingX is added to the same miscellaneous income as domestic profit.
The NTA asks domestic dealers to issue an annual transaction report, but overseas exchanges do not issue one. FAQ 2-7 tells you to confirm amounts from bank deposits and withdrawals, trade history and published market prices.
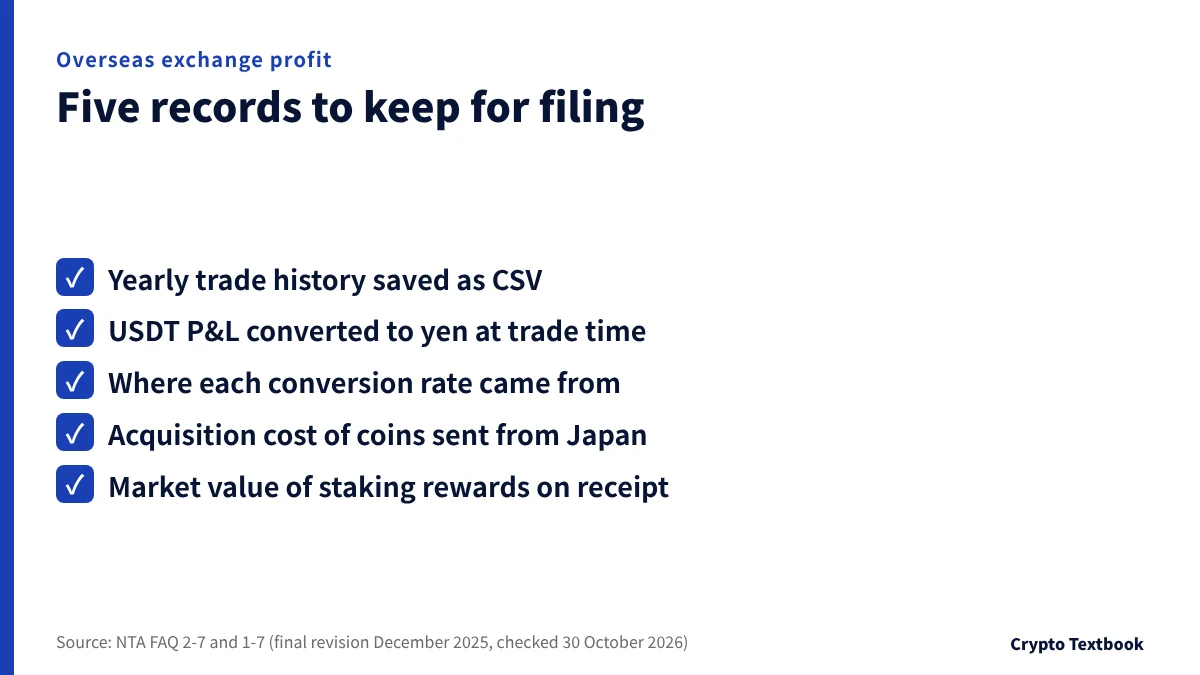
- Save trade history (spot, futures, deposits, withdrawals, fees) as CSV for each year
- Convert USDT-denominated P&L to yen at the rate at the time of each trade
- Note where each conversion rate came from (which exchange's price)
- For coins sent from a domestic exchange, carry over the domestic acquisition cost
- Record coins received from staking and similar at their market value on receipt
If you have no history and cannot confirm the acquisition cost, you may use 5% of the sale price (FAQ 2-7). Sell for JPY 5 million and the cost is JPY 250,000, so JPY 4.75 million is income.
Overseas trades can also be identified
The Crypto-Asset Reporting Framework (CARF) is an international standard for exchanging crypto trading information between tax authorities. Each authority collects non-residents' information from its own dealers and passes it to the country where they live.
In Japan, declaring your country of residence to dealers became required from 1 January 2026. Domestic dealers report to the tax office by 30 April each year from 2027 (NTA CARF page).
Penalty for failure to file
A return filed after the deadline is treated as late, and a penalty for failure to file applies (No.2024).
| When you file | Up to JPY 0.5m | JPY 0.5m to 3m | Above JPY 3m |
|---|---|---|---|
| On your own before audit notice | 5% | 5% | 5% |
| After notice, before the audit | 10% | 15% | 25% |
| After the audit | 15% | 20% | 30% |
※ Rates apply to each portion of the tax due. Delinquency tax is also charged until payment.
Will the tax office find overseas crypto profit? CARF and tax audits
How to check on official screens: three NTA pages
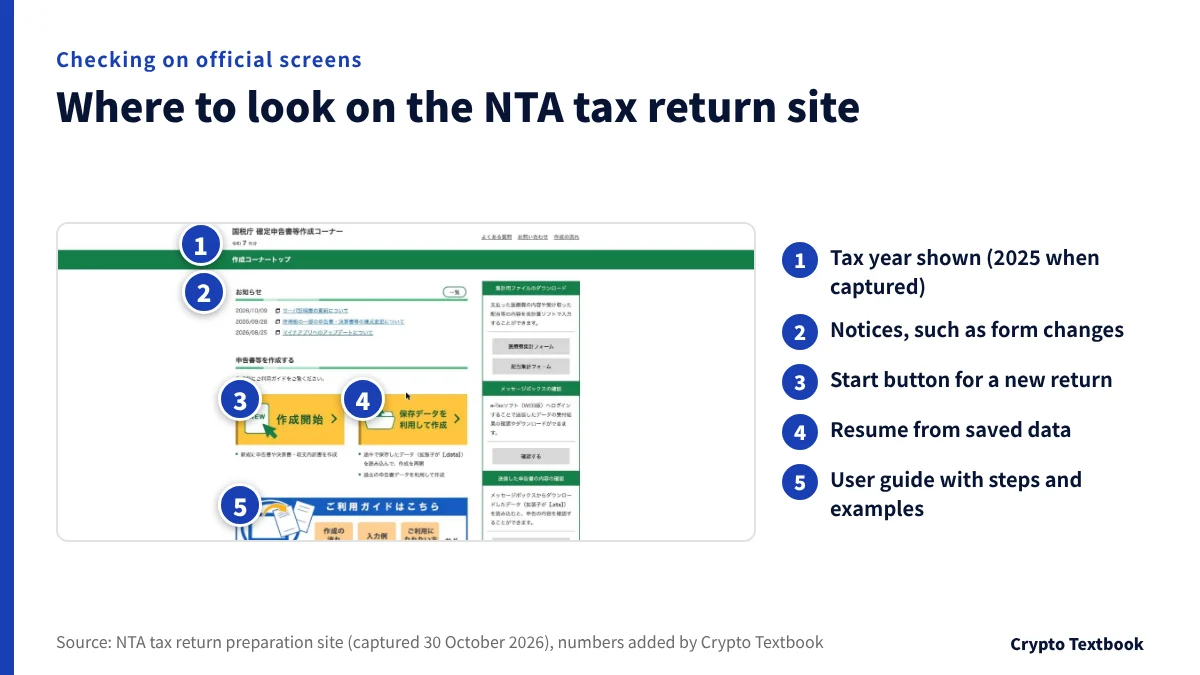
National Tax Agency pages state which date's law they are based on. Use these three pages to check the current rules.
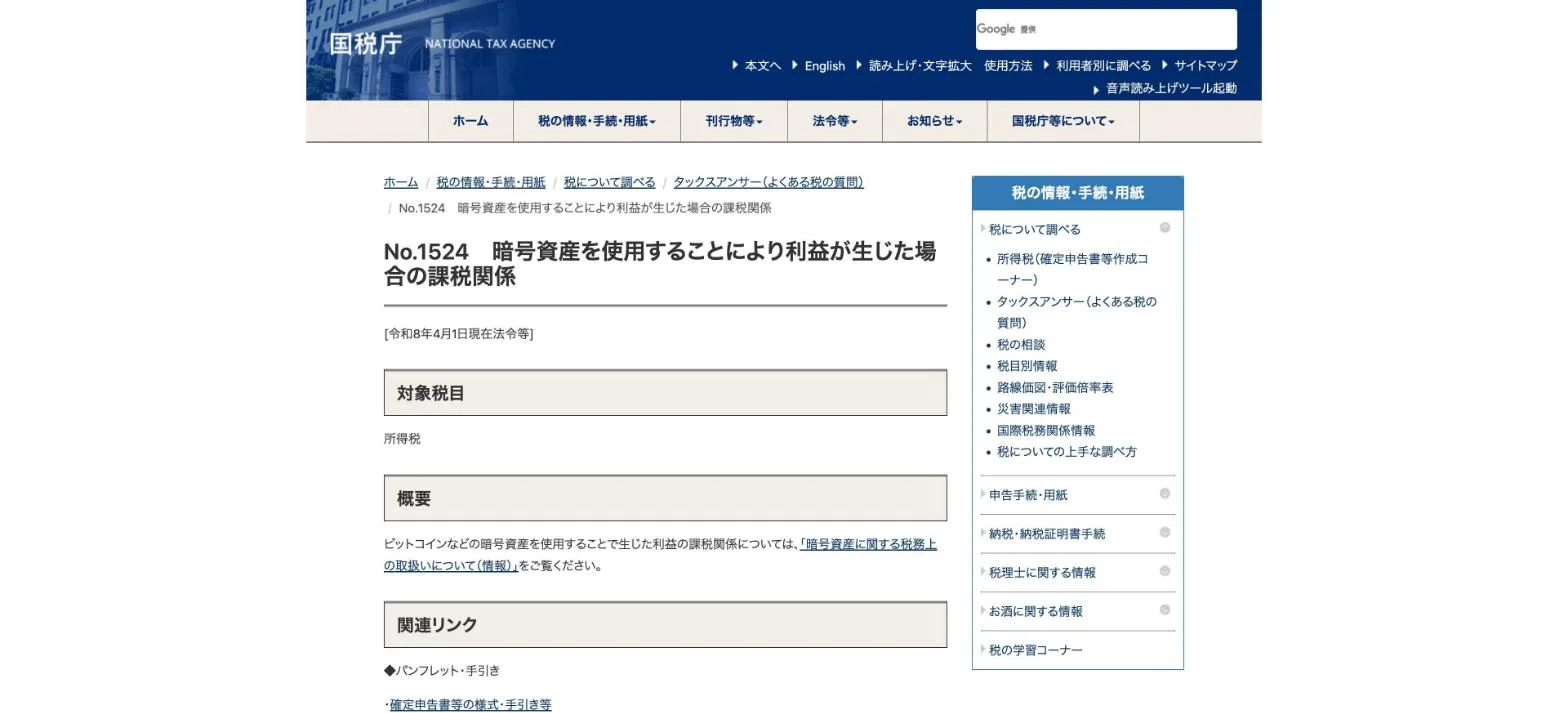
- 01Open Tax Answer No.1524
This is the NTA entry page for crypto taxation. The date line at the top, law as of 1 April 2026, shows which year's law applies.
- 02Find your transaction in the FAQ PDF
The FAQ is the final revision of December 2025. Each transaction has its own question, such as 1-1 for selling and 1-3 for swapping.
- 03Enter figures on the return preparation site
Check that the tax year at the top left matches the year you are filing. To start a new return, use the start button.
On 30 October 2026, the site showed the 2025 tax-year screens. Returns for 2026 are made on the 2026 tax-year screens.
Our verdict: what to do in each situation
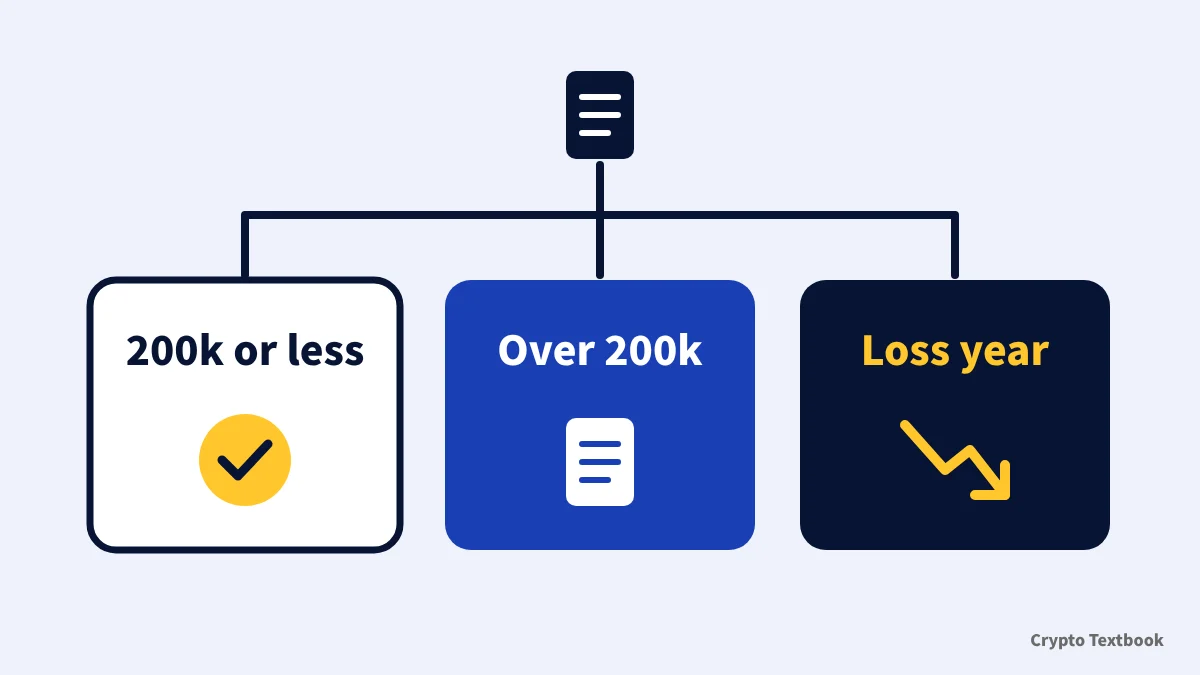
Profit made in 2026, including on overseas exchanges, is filed as miscellaneous income. The 20% separate taxation does not cover 2026. Estimate your tax at aggregate rates and have your records ready to file early in the new year.
- One employer and profit of JPY 200,000 or less: no income tax return, but file for resident tax
- Profit above JPY 200,000: file between 16 February and 15 March of the next year
- Loss-making year: offset only within miscellaneous income in that year, and keep records
- Unsure whether to wait for separate taxation: the earliest start is 1 January 2027, and the date is fixed only by Cabinet Order
- Overseas exchanges only: save history each year and convert to yen
Frequently asked questions
Q. From how much profit is crypto taxed in Japan?
A. Profit of any size is taxable. Employees paid by one employer do not need to file an income tax return if income other than salary is JPY 200,000 or less a year (No.1900). A resident tax filing is still needed below that amount.
Q. What is the tax rate on Bitcoin profit?
A. Profit made in 2026 is taxed on an aggregate basis: income tax of 5% to 45% plus 10% resident tax. The rate depends on your total taxable income, up to 55% combined. The 20% separate taxation applies only to trades from the start date.
Q. Is crypto taxed if I just hold it?
A. No. Tax arises when you give it up by selling, swapping for another crypto asset or paying with it (FAQ 1-1 to 1-3). Moving coins to your own wallet is not taxed either.
Q. When does 20% separate taxation on crypto start?
A. It applies to trades from 1 January of the year after the amended Financial Instruments and Exchange Act takes effect. The date is set by Cabinet Order within one year of promulgation and was not fixed as of 30 October 2026. It starts on 1 January 2027 if the Act takes effect in 2026, or 1 January 2028 if in 2027. 2026 trades follow current rules either way.
Q. Is swapping into USDT taxable?
A. Yes. Swapping BTC for USDT is a swap between crypto assets, and income is calculated at the market value at the time (FAQ 1-3). It is income for that year even if you never convert to yen.
Q. Can crypto losses be carried forward?
A. Not under the current system. Losses in miscellaneous income cannot be offset against salary or other income either (No.2250). The outline proposes a 3-year carry-forward for losses on specified crypto assets from the start date.
Q. Do I have to report profit on overseas exchanges?
A. Yes. Most residents are taxed in Japan on income arising abroad (No.2010). Overseas exchanges do not issue an annual transaction report, so save your trade history and convert it to yen yourself (FAQ 2-7).
Q. What happens if I forget to file?
A. The return is treated as late and a penalty for failure to file applies. It is 5% if you file on your own before notice of an audit and 15% to 30% after an audit (No.2024). Delinquency tax is also charged until payment.
Sources and conditions
- National Tax Agency: FAQ on the tax treatment of crypto assets, final revision December 2025 (PDF, checked 30 October 2026) →
- National Tax Agency: tax treatment of crypto assets and calculation sheets (December 2025) →
- National Tax Agency: Tax Answer No.1524, taxation of profit from using crypto assets →
- National Tax Agency: Tax Answer No.1900, salaried employees who must file →
- National Tax Agency: meaning of cases where a return is not required (No.1900 Q&A) →
- National Tax Agency: Tax Answer No.2260, income tax rates →
- National Tax Agency: Tax Answer No.2250, offsetting income and losses →
- National Tax Agency: Tax Answer No.2024, if you forget to file →
- National Tax Agency: Tax Answer No.2010, individuals liable to tax →
- National Tax Agency: Crypto-Asset Reporting Framework (CARF) information →
- National Tax Agency: tax return preparation site (captured 30 October 2026) →
- Ministry of Finance: FY2026 Tax Reform Outline (Cabinet decision of 26 December 2025, PDF) →
- Ministry of Finance: tax reform laws in the 221st Diet (Income Tax Act amendment passed 31 March 2026) →
- Ministry of Finance: summary of the bill amending the Income Tax Act (PDF) →
- Ministry of Finance: Act amending the Income Tax Act and related laws (PDF, supplementary provisions Article 1 items 10 and 11) →
- Financial Services Agency: bills in the 221st Diet (passed 15 July 2026) →
- Financial Services Agency: explanatory material on the bill amending the Financial Instruments and Exchange Act (PDF, effective dates) →
- Ministry of Internal Affairs and Communications: individual resident tax (10% income-based rate) →
- Kobe City: resident tax filing for individuals →
FX Textbook is an independent information site, not an exchange or a provider of personal investment advice. Crypto-asset trading involves risk: price moves, liquidation of leveraged positions, transfer errors and exchange operating risk can result in the loss of some or all invested capital.
NEXT STEP
Know the tax rules? Compare the exchanges next.
Spot and futures fees, maximum leverage, liquidation rules and customer support, organised exchange by exchange.
Listed exchanges