
You made a profit on crypto this year and want to know what you can legally do about the tax bill before 31 December.
For a resident of Japan, the legal options come down to four things: when you realise gains, offsetting losses, expenses and income deductions, and records and filing. Holding is not taxed; selling, swapping or paying with crypto is taxed as miscellaneous income in that year (National Tax Agency FAQ, revised December 2025).
This article lists eight measures using only National Tax Agency and Ministry of Finance documents, with worked examples on assumed figures, so you know what to check before the year ends.
Summary: four ideas decide crypto tax in Japan
- Timing: tax applies in the year you sell, swap or pay; holding alone is not taxed
- Offsetting: gains and losses net within miscellaneous income in the same year; no carry-forward
- Expenses and deductions: trading fees and deductions such as iDeCo contributions reduce taxable income
- Records: without a history, cost may be set at 5% of the sale price, which inflates income
| Common belief | Treatment in NTA documents |
|---|---|
| No tax until you convert to yen | False: crypto-to-crypto swaps are taxed (FAQ 1-3) |
| Losses can be pushed to next year | False: miscellaneous-income losses cannot be carried forward (FAQ 2-11) |
| Gifts to family avoid tax | False: the giver records market value as revenue (FAQ 1-4, 2-10) |
| Holding alone is not taxed | True: no income arises until you dispose of the crypto |
The rules were checked against National Tax Agency and Ministry of Finance publications on 14 November 2026. Your tax depends on your total income and deductions. In a large-profit year, talk to a tax accountant or the tax office before filing.
Is just holding crypto taxed in Japan? When tax applies
Crypto gains are classified in principle as miscellaneous income (FAQ 2-2). They are added to salary and other income, so income tax of 5% to 45% applies plus 10% resident tax.
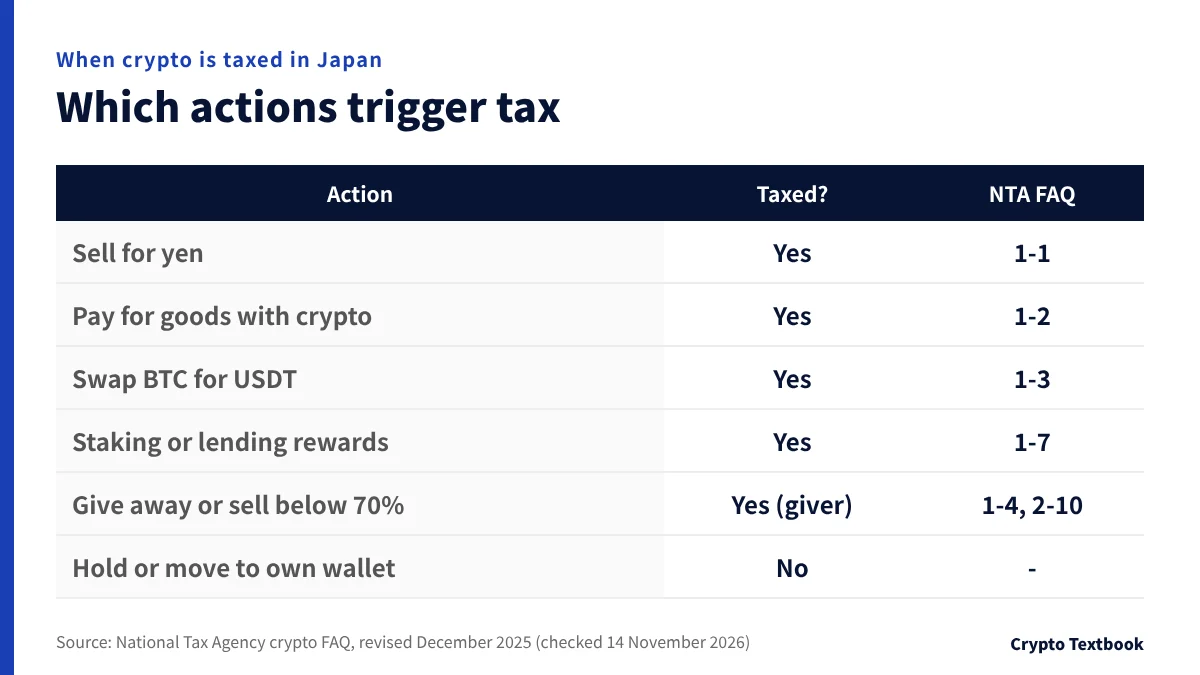
Tax is triggered when you let go of the crypto. An unrealised gain creates no income until you sell, swap or spend.
| Action | Taxed? | NTA FAQ |
|---|---|---|
| Sell for yen | Yes | 1-1 |
| Buy goods or services with crypto | Yes | 1-2 |
| Swap BTC for USDT or another coin | Yes | 1-3 |
| Receive staking or lending rewards | Yes (market value when received) | 1-7 |
| Give it away, or sell below 70% of market value | Yes (for the giver) | 1-4, 2-10 |
| Keep holding, or move between your own accounts | No | (no disposal) |
The tax year is, in principle, the year the sold crypto is delivered. You may instead choose the year of the contract (FAQ 2-1). If you sell late on 31 December, check the trade and settlement dates in your statement.
When you swap appreciated BTC into USDT, you have disposed of the BTC. It counts as that year's income even if you never convert to yen.
Crypto tax basics in Japan: miscellaneous income, rates and calculation →
Eight legal ways to reduce crypto tax in Japan
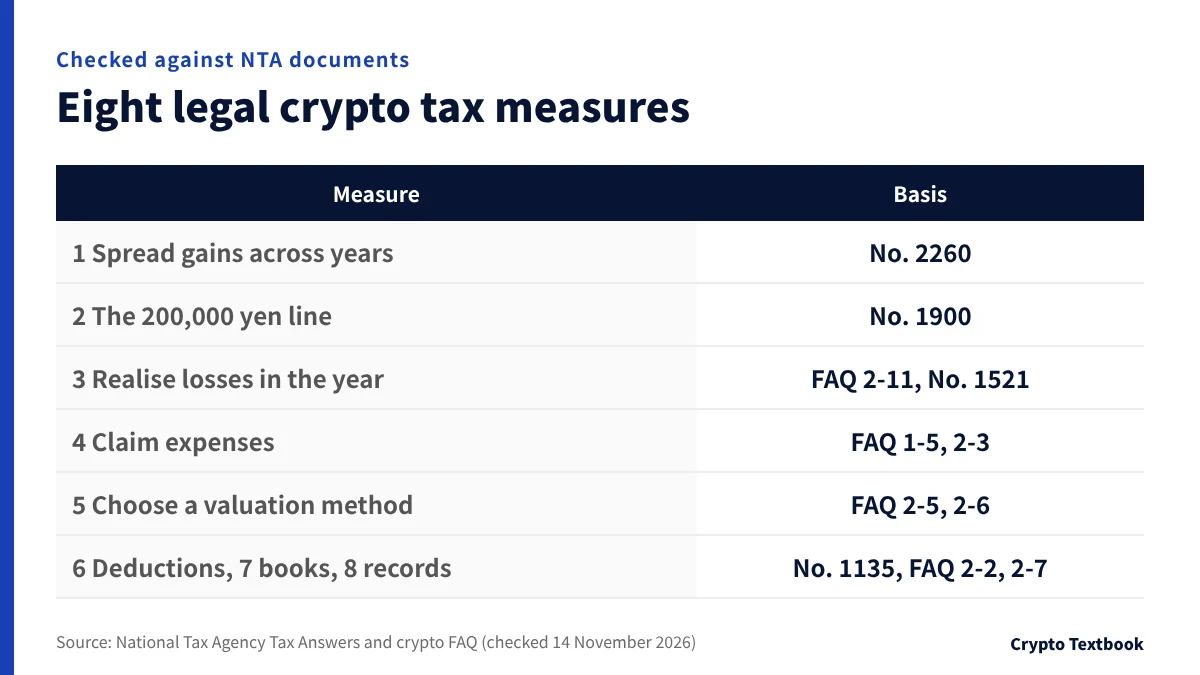
Each measure below is grounded in a National Tax Agency document. None guarantees a saving, and none should drive a trading decision on tax grounds alone.
| Measure | When it helps | Basis |
|---|---|---|
| 1. Spread gains across tax years | Gains would bunch into one year | No. 2260 |
| 2. Know the 200,000 yen line | Employees with one employer and year-end adjustment | No. 1900 |
| 3. Realise losses within the year | Gains and unrealised losses in the same year | FAQ 2-11, No. 1521 |
| 4. Claim every expense | You pay trading fees, line charges and so on | FAQ 1-5, 2-3 |
| 5. Choose a valuation method on time | You trade the same coin repeatedly | FAQ 2-5, 2-6 |
| 6. Use income deductions | iDeCo, hometown tax donations and similar | No. 1135, No. 1150 |
| 7. Keep books above 3 million yen | Total proceeds are large | FAQ 2-2, No. 2072 |
| 8. Keep records and file on time | Everyone | FAQ 2-7, No. 2024 |
Measures 1 to 3 are about when you realise gains, 4 to 7 about how taxable income is calculated, and 8 about avoiding penalties for late or missing returns.
Measures 1 and 2: spread gains and the 200,000 yen line
Measure 1: spread gains across tax years
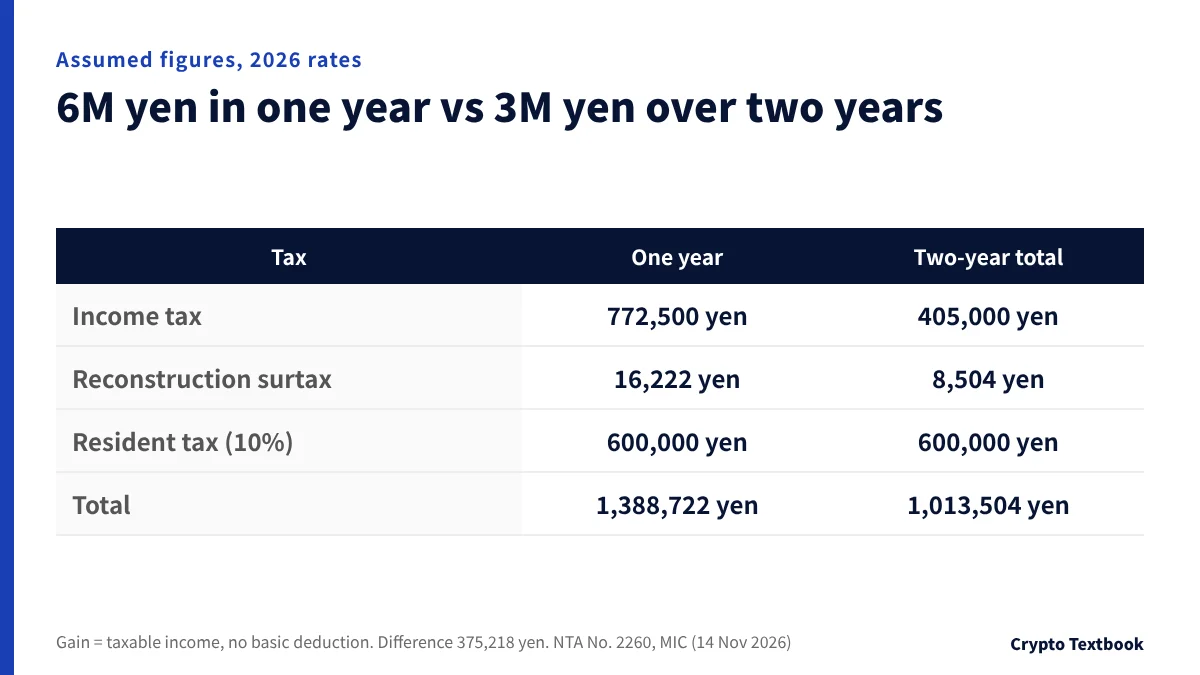
Japanese income tax has seven brackets from 5% to 45% (Tax Answer No. 2260). The same total gain reaches higher brackets when it is realised in a single year.
| Assumed figures | 6 million yen in one year | 3 million yen in each of two years |
|---|---|---|
| Income tax (bracket table) | 772,500 yen | 202,500 yen x 2 |
| Reconstruction surtax (2.1%) | 16,222 yen | 4,252 yen x 2 |
| Resident tax (10%) | 600,000 yen | 300,000 yen x 2 |
| Total | 1,388,722 yen | 1,013,504 yen |
In this example, spreading the gain over two years lowers the total by 375,218 yen. Next year's price is unknown, though. If you delay a sale and the price falls, the loss can exceed the tax difference.
Measure 2: the 200,000 yen line for employees
- Applies to employees paid by one employer whose tax is settled by year-end adjustment
- If income other than salary and retirement income totals 200,000 yen or less, no income tax return is required (No. 1900)
- Different conditions apply if you are paid by two or more employers or your salary exceeds 20 million yen (No. 1900)
- Even when no income tax return is needed, check with your municipality whether a resident tax declaration is required
The line is measured on income, not on proceeds. It is the amount after expenses such as trading fees.
From what amount is crypto taxed in Japan? The 200,000 yen rule →
Measure 3: realise losses before 31 December to offset gains
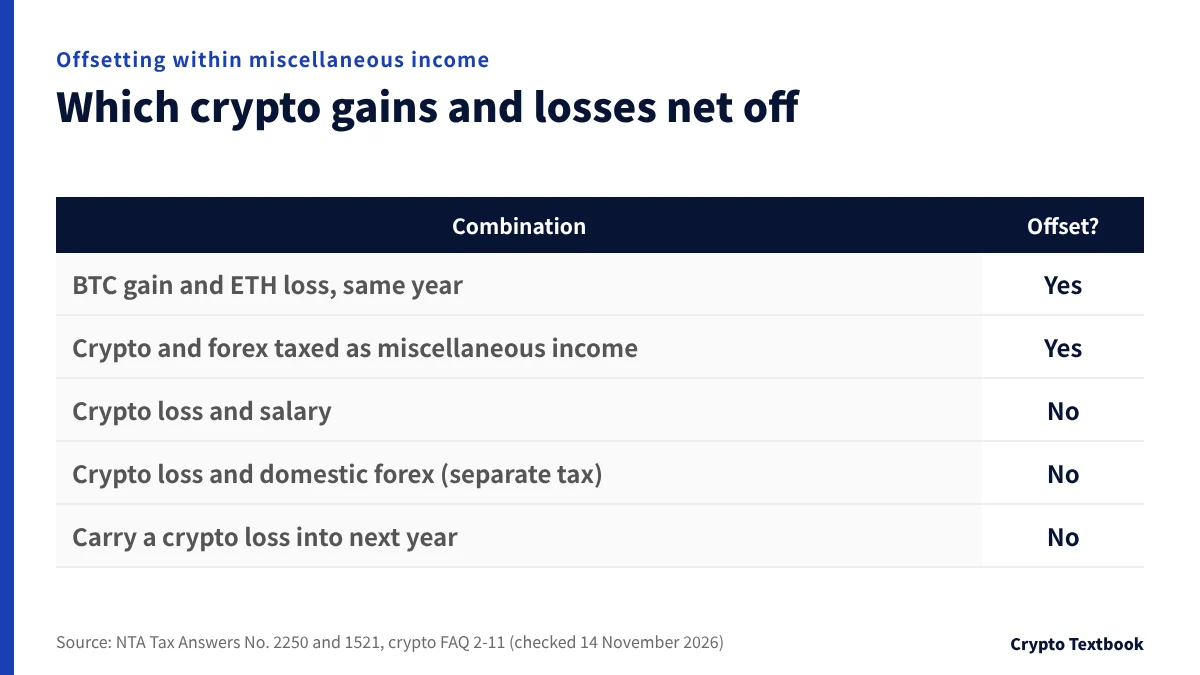
A miscellaneous-income loss cannot be deducted from salary or other income (No. 2250, FAQ 2-11). Within the same year's miscellaneous income, however, gains and losses on different coins net off.
| Combination | Offset? |
|---|---|
| BTC gain and ETH loss in the same year | Yes (same miscellaneous income) |
| Crypto gain and a forex loss taxed as miscellaneous income | Yes (No. 1521 allows netting within miscellaneous income) |
| Crypto loss and salary income | No |
| Crypto loss and domestic forex gains under separate taxation | No (No. 1521) |
| This year's crypto loss into next year | No carry-forward |
No. 1521 says over-the-counter forex not traded with a Type I financial instruments business operator in Japan is generally miscellaneous income. Whether a given offshore broker falls under this depends on the trade.
On assumed figures, take a year with an 800,000 yen gain on BTC and a 300,000 yen unrealised loss on ETH. Selling the ETH in December leaves 500,000 yen of miscellaneous income. Selling it in January leaves the full 800,000 yen for this year.
Whether to buy the coin back straight away is an investment decision. Price moves and fees can cost more than the tax you offset.
Can crypto losses be carried forward in Japan? Offsetting rules →
Measures 4 and 5: expenses and the valuation method
Measure 4: claim every expense
| Spending | Treatment |
|---|---|
| Fee when buying | Added to cost (e.g. 2,000,000 yen + 550 yen fee = 2,000,550 yen, FAQ 1-5) |
| Fee when selling | Deductible expense (FAQ 2-3) |
| Internet and phone charges | Only the part clearly attributable to crypto trading |
| Computer purchase | The part directly needed; expensive items are depreciated over years |
For shared personal and trading costs, keep the basis for the split. Save receipts and a note of how you calculated the ratio.
Measure 5: choose a valuation method on time
The cost of what you sold is calculated by the total-average or moving-average method. Without a notification, the total-average method applies (FAQ 2-5).
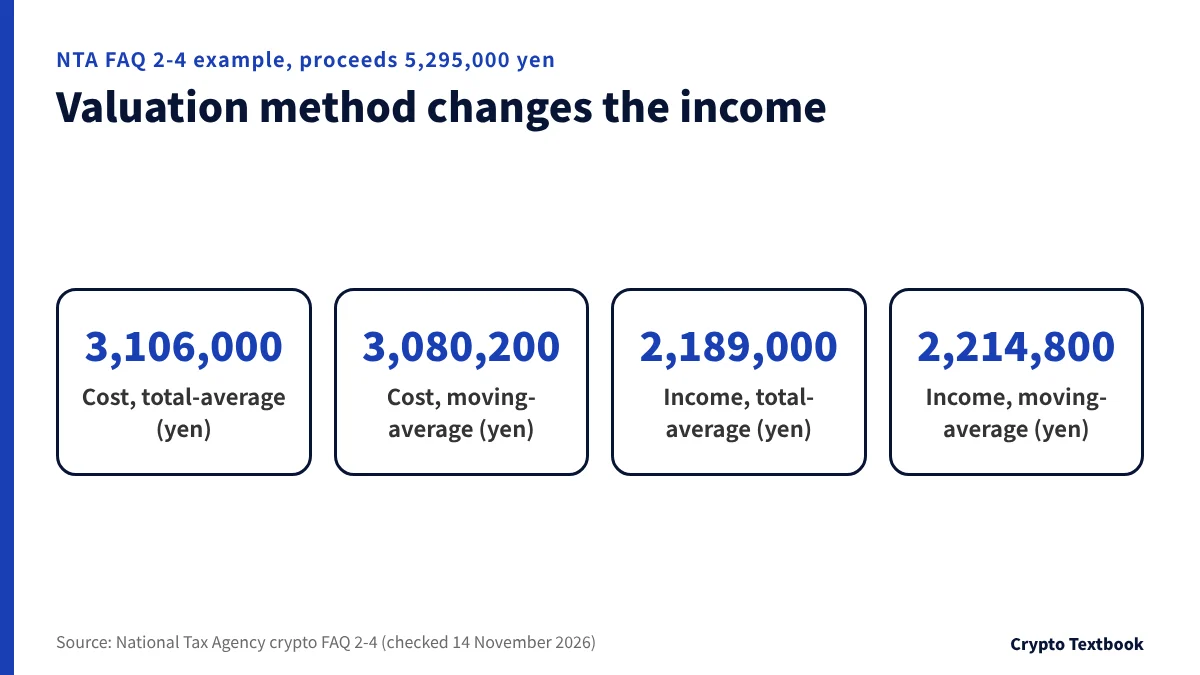
| NTA FAQ 2-4 example | Total-average | Moving-average |
|---|---|---|
| Proceeds for the year | 5,295,000 yen | 5,295,000 yen |
| Cost of sales | 3,106,000 yen | 3,080,200 yen |
| Income | 2,189,000 yen | 2,214,800 yen |
- To use the moving-average method, file the notification by the return deadline for the year you first acquired crypto, normally 15 March of the next year (A1-20)
- The method is chosen per coin; the same deadline applies in the year you acquire a new coin
- To change an existing method, apply for approval by 15 March of the year of change (A1-24)
- An application may be rejected if the current method has been used for less than three years (FAQ 2-6)
In the FAQ example the total-average method gives 25,800 yen less income, but a different order of trades can reverse that. Work out both on your own trades before choosing.
Measures 6 and 7: income deductions and bookkeeping
Measure 6: use income deductions
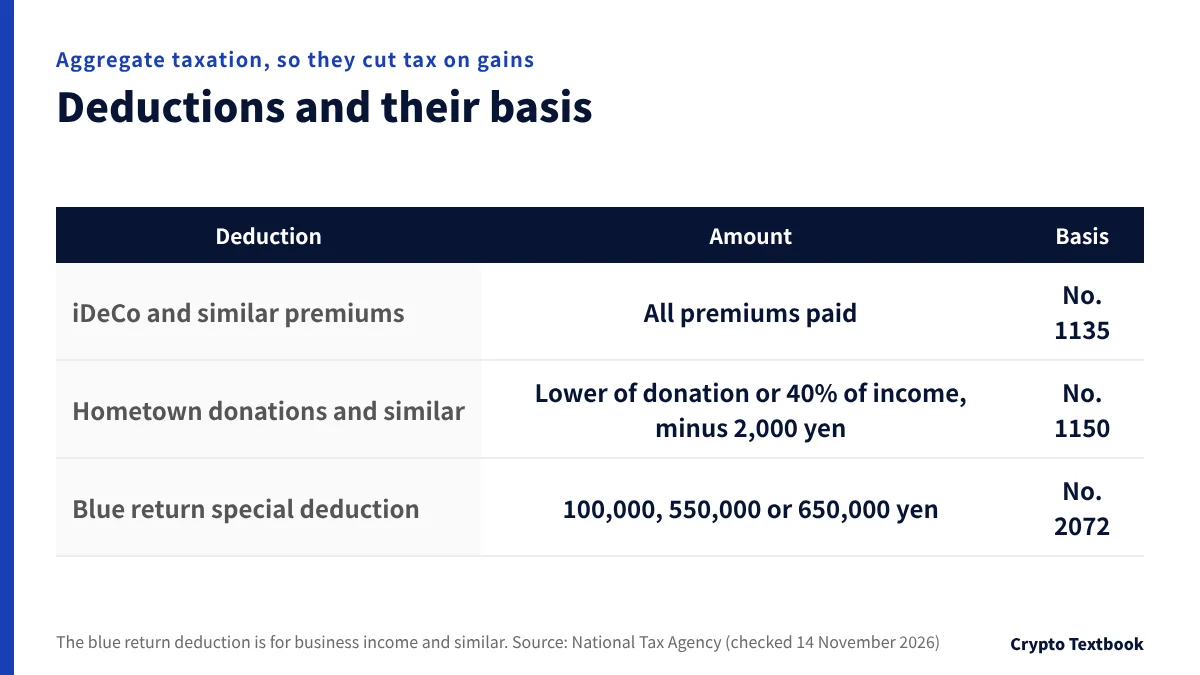
Because crypto gains are taxed together with other income, income deductions come off the total, crypto gains included. The higher your bracket in a profitable year, the more a deduction saves.
| Deduction | Amount deducted | Basis |
|---|---|---|
| Small enterprise mutual aid premiums (including iDeCo contributions) | All contributions paid in the year | No. 1135 |
| Donation deduction (including hometown tax donations) | Lower of donations or 40% of total income, minus 2,000 yen | No. 1150 |
| Donating crypto to a certified NPO | Market value is the donation; the coin's gain is income | FAQ 1-4 |
The resident tax side of hometown tax donations is not covered in this table. Check the limit with the Ministry of Internal Affairs and Communications and the municipality.
Measure 7: keep books when proceeds exceed 3 million yen
- If the year's trading revenue exceeds 3 million yen and you keep books, it is in principle business income (FAQ 2-2)
- Without books, it is in principle miscellaneous income from a business activity
- Even with books, cases lacking a profit motive are judged individually
- Blue-return filers with business income may get a 100,000, 550,000 or 650,000 yen special deduction (No. 2072)
Blue returns require prior approval and double-entry bookkeeping. Whether you have business income is judged case by case, so consult a tax accountant if your trading is large.
Measure 8: keep records and file on time
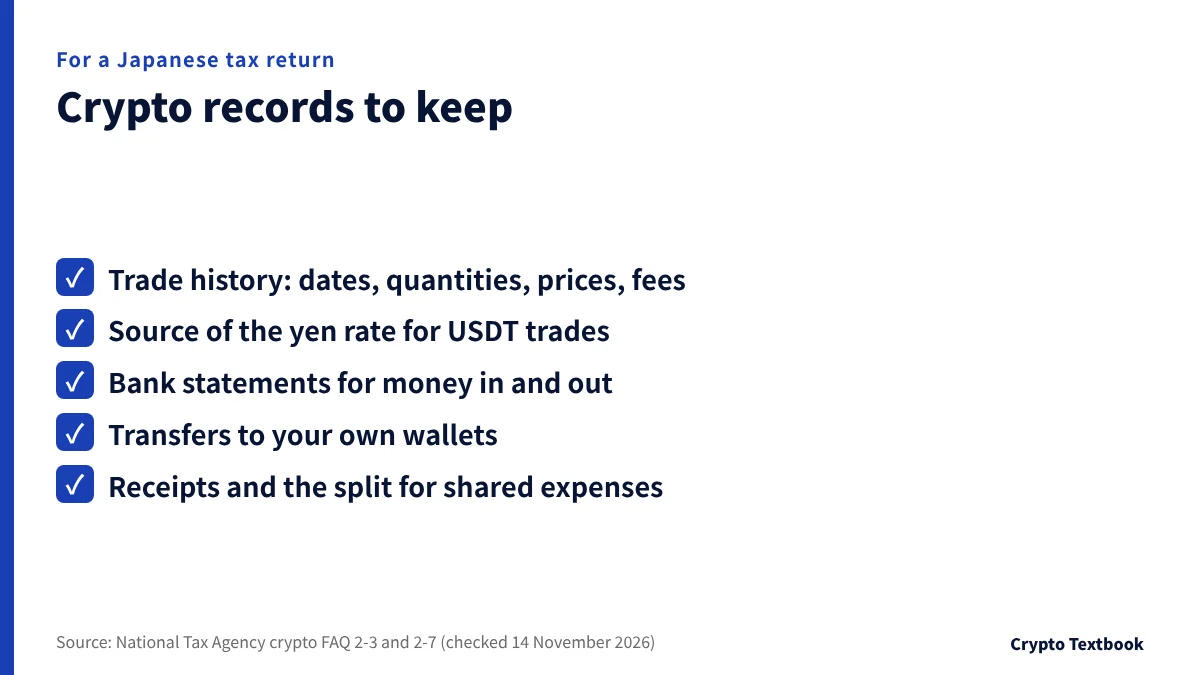
The National Tax Agency asks domestic crypto exchanges in Japan to issue annual trading reports (FAQ 2-7). For trades on overseas exchanges, you confirm the cost and sale prices yourself.
- Download your trade history (dates, quantities, prices, fees) before the year ends
- For USDT-quoted trades, keep the source of the yen exchange rate you used
- Keep bank statements showing money in and out when you bought or sold
- Keep records of transfers to your own wallets: not taxed, but needed to reconcile quantities
Without records, cost may be set at 5% of the sale price (FAQ 2-7). A 5 million yen sale then has a cost of 250,000 yen. The more you actually paid, the more this overstates your income.
| When the late return is filed | Penalty for failure to file (2023 tax year onward) |
|---|---|
| Voluntarily, before any audit notice | 5% |
| After notice, before the audit | 10% (15% on 0.5M to 3M yen; 25% above 3M yen) |
| After the audit | 15% (20% on 0.5M to 3M yen; 30% above 3M yen) |
According to the National Tax Agency, field audits of individuals trading crypto and similar assets numbered 613 in the July 2024 to June 2025 operational year. The average additional tax per case was 7.45 million yen.
When does the 20% separate crypto tax start in Japan?
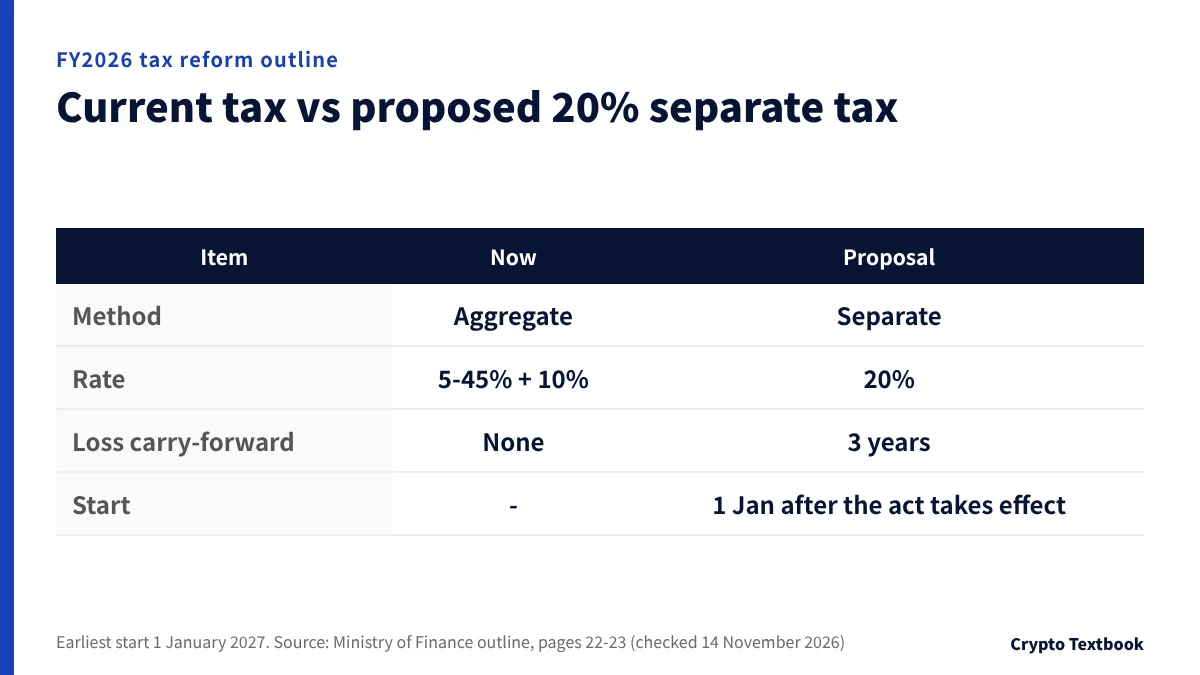
The FY2026 tax reform outline proposes taxing gains on the transfer of specified crypto assets separately from other income at 20% (15% income tax and 5% resident tax). Unused losses could be carried forward for three years.
| Item | Now (2026 tax year) | Outline proposal |
|---|---|---|
| Method | Miscellaneous income, aggregate taxation | Separate self-assessment taxation |
| Rate | Income tax 5-45% plus 10% resident tax | 20% (15% income tax, 5% resident tax) |
| Loss carry-forward | None | Three years |
| Scope | All crypto assets | Transfers of specified crypto assets to a crypto asset trading business (provisional name) |
It applies from 1 January of the year after the amended Financial Instruments and Exchange Act takes effect (supplementary provisions, Article 1, of the act amending the Income Tax Act). The effective date will be set by Cabinet Order and is not yet fixed.
- If the amended act takes effect during 2026: from 1 January 2027 (the earliest case)
- If it takes effect during 2027: from 1 January 2028
- Either way, 2026 trades are filed under today's aggregate taxation
- The outline does not say whether trades on overseas exchanges are covered
The outline has no rule for bringing pre-reform losses into the new system. If you plan to wait for separate taxation, remember that both the start date and the scope are still open.
What does not work: gifts, other names, not filing
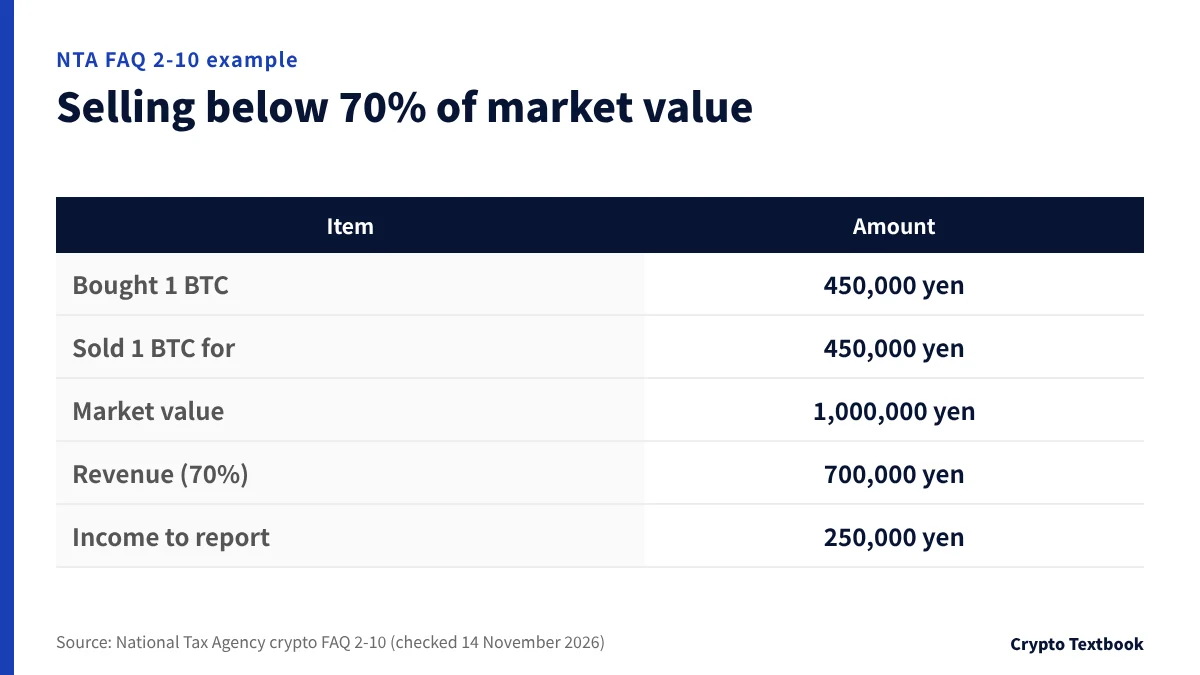
The idea that giving crypto to family lowers tax does not match the National Tax Agency's guidance. A person who gives crypto records its market value at the time as revenue (FAQ 1-4).
| NTA FAQ 2-10 example | Amount |
|---|---|
| Bought 1 BTC on 9 April | 450,000 yen |
| Sold 1 BTC on 20 May | 450,000 yen |
| Market value of 1 BTC at sale | 1,000,000 yen |
| Revenue recorded (70% of market value) | 700,000 yen |
| Income to report | 250,000 yen |
Selling below 70% of market value means the gap up to 70% is added to revenue. The family member who receives the crypto may also owe gift tax (FAQ 4-1).
- Not declaring overseas exchange gains: residents of Japan are taxed on worldwide income (FAQ 1-8)
- Treating crypto never converted to yen as tax-free: a swap is taxed (FAQ 1-3)
- Splitting trades across accounts in relatives' names: income belongs to whoever traded
- Cashing out in small amounts: the test is the total for the year
- Deleting or not keeping history: cost may end up at 5% of the sale price
Under CARF, each country's tax authority collects data on non-residents from its own crypto providers and passes it to the country of residence. In Japan, anyone trading with a domestic crypto exchange on or after 1 January 2026 must file a declaration of their country of residence with that exchange.
For crypto held by a company, assets with an active market are marked to market at year end (FAQ 3-1-3). Corporate tax can apply to unrealised gains, so it is not a like-for-like comparison with an individual.
Will overseas exchange crypto profits be found? CARF and tax audits →
Our verdict: what to do first, by situation
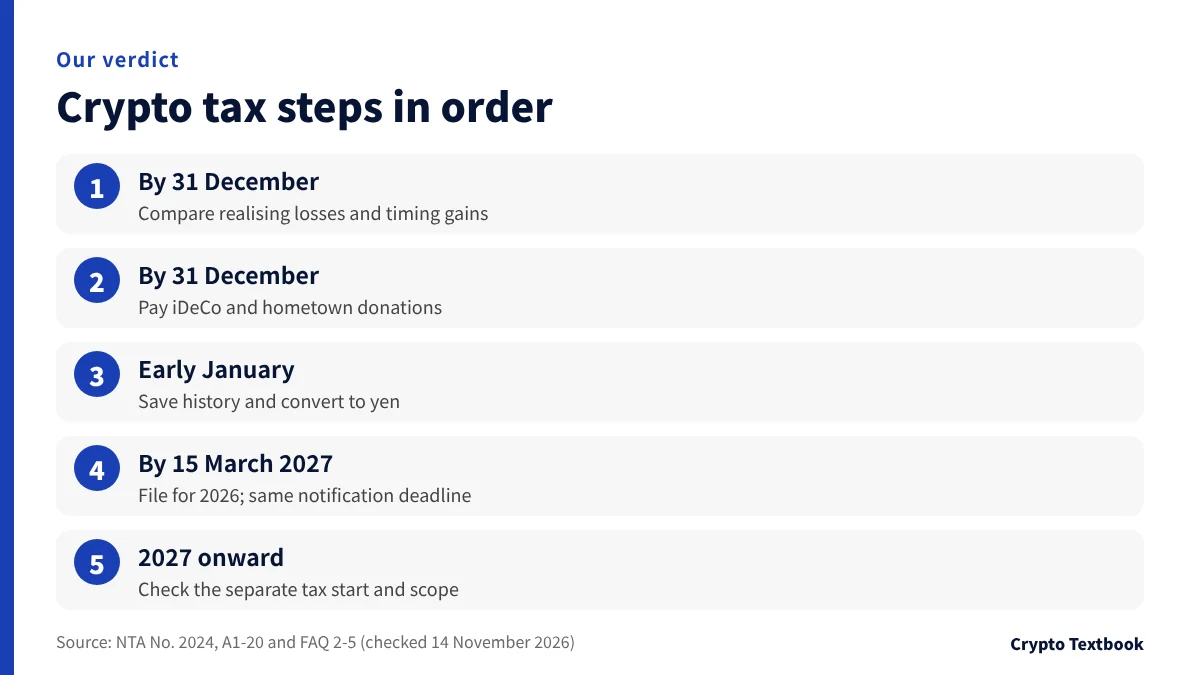
Employees with gains around 200,000 yen should first check whether income after expenses requires a return. Those with gains in the millions should compare realising losses and deferring gains before 31 December. Frequent traders of one coin should check the valuation notification deadline first.
| When | What to do |
|---|---|
| By 31 December | Realise losses, decide timing of gains, pay iDeCo and hometown donations |
| Early January | Save exchange history, convert to yen, organise expense receipts |
| By 15 March 2027 | File the 2026 return (from 16 February); valuation notification for the first year |
| 2027 onward | Watch for the start date and scope of separate taxation |
Crypto prices are volatile, and futures or leveraged trading can lose more than you deposit. Do not take a trading loss larger than the tax you were trying to save.
Frequently asked questions
Q. Is just holding crypto taxed in Japan?
A. No. Income tax applies to the gain when you sell, swap or spend crypto (NTA FAQ 1-1 to 1-3). Moving it between your own accounts or wallets is not taxed.
Q. What can I do before the year ends to lower crypto tax in Japan?
A. Sell coins with unrealised losses to offset this year's gains, compare deferring gains to next year, and pay iDeCo contributions or hometown tax donations within the year. After 31 December, none of these count for 2026.
Q. Is there a loophole in Japanese crypto tax?
A. No. A gift makes the giver record market value as revenue (FAQ 1-4, 2-10), and swaps are taxed (FAQ 1-3). Not filing adds penalties and late-payment tax (No. 2024).
Q. Can crypto losses offset forex gains?
A. If both are miscellaneous income, they net within the same year. NTA No. 1521 treats OTC forex not traded with a Type I financial instruments business operator as generally miscellaneous income. Domestic forex under separate taxation cannot be offset.
Q. Can crypto losses be carried forward in Japan?
A. Not under current rules (FAQ 2-11). The FY2026 outline proposes a three-year carry-forward for specified crypto assets, applying from 1 January after the amended act takes effect, and that date is not yet fixed.
Q. Should I use the total-average or moving-average method?
A. Calculate both on your own trades. In NTA FAQ 2-4 the total-average method gives 25,800 yen less income, but trade order can reverse that. To use the moving-average method, file the notification by the return deadline for your first year.
Q. Do these measures apply to overseas exchanges?
A. Yes. Residents of Japan are taxed on worldwide income using the same calculation (FAQ 1-8). Overseas exchanges do not send Japanese annual reports, so keep your history and yen conversion basis yourself (FAQ 2-7).
Sources
- National Tax Agency (Japan) | Tax treatment of crypto assets, etc.: FAQ, last revised December 2025 (PDF, Japanese, checked 14 November 2026) →
- National Tax Agency (Japan) | Tax treatment of crypto assets and calculation sheets (December 2025, Japanese) →
- National Tax Agency (Japan) | Tax Answer No. 2260: Income tax rates (Japanese) →
- National Tax Agency (Japan) | Tax Answer No. 1900: Salaried employees who must file a return (Japanese) →
- National Tax Agency (Japan) | Tax Answer No. 2250: Offsetting profits and losses (Japanese) →
- National Tax Agency (Japan) | Tax Answer No. 1521: Taxation of foreign exchange margin trading (Japanese) →
- National Tax Agency (Japan) | Tax Answer No. 1135: Small enterprise mutual aid premium deduction (Japanese) →
- National Tax Agency (Japan) | Tax Answer No. 1150: Donation deduction (Japanese) →
- National Tax Agency (Japan) | Tax Answer No. 2072: Blue return special deduction (Japanese) →
- National Tax Agency (Japan) | Tax Answer No. 2024: Filing after the deadline (Japanese) →
- National Tax Agency (Japan) | A1-20 Notification of the crypto asset valuation method (Japanese) →
- National Tax Agency (Japan) | A1-24 Application to change the crypto asset valuation method (Japanese) →
- National Tax Agency (Japan) | Automatic exchange of information under CARF (Japanese) →
- National Tax Agency (Japan) | Status of income tax and consumption tax audits, FY2024 operational year (PDF, Japanese) →
- Ministry of Finance (Japan) | Outline of the FY2026 Tax Reform (PDF, Japanese) →
- Ministry of Finance (Japan) | Tax reform bills submitted to the 221st Diet session (Japanese) →
- Ministry of Internal Affairs and Communications (Japan) | Individual resident tax (Japanese) →
FX Textbook is an independent information site, not an exchange or a provider of personal investment advice. Crypto-asset trading involves risk: price volatility, liquidation of leveraged positions, transfer mistakes and the operational risk of exchanges and service providers can cause you to lose some or all of your invested capital. No result is guaranteed.
NEXT STEP
Before you use an exchange, check its conditions and operator information.
Operating entity, fees, leverage and liquidation, funding and KYC requirements, organised exchange by exchange.
Exchanges related to this column
Fees, leverage, funding options and current offers are on each exchange page.